

Every carbon exchange looks fine at 200 trades a day. The order book renders, settlement clears, the registry syncs, and nobody questions the architecture underneath it. Then volume triples in a single compliance-driven quarter, three new registries get added, and the same platform that felt production-ready starts throwing errors nobody can explain. This is not a bad luck story. It is a carbon exchange scalability problem, and it is almost always predictable months before it becomes visible to traders. We have architected and built live carbon market infrastructure – Carbon Plant, an FSA-registered NFT-based carbon credit exchange, and Planet First Registry, the registry layer underneath it. What follows is the failure map we walk exchange CTOs and operators through when their existing platform starts showing cracks: the twelve places carbon exchange scalability actually breaks, why each one is harder in carbon markets than in a typical trading system, and what an honest fix looks like. If your platform is handling growing order flow, adding registries, or onboarding institutional counterparties and you are seeing timeouts, mismatched balances, or settlement delays, this is written for you. Why Carbon Exchange Scalability Is a Different Problem Than Exchange Scalability A commodities exchange scales by adding compute. A carbon exchange has to scale a much messier dependency chain: registry data that arrives asynchronously, credits with vintage/methodology/geography attributes that change eligibility mid-trade, and settlement that depends on external systems the exchange doesn’t control. Generic trading infrastructure assumes the asset is fungible the moment it clears the order book. Carbon credits are not. Two “identical” tonnes can have different corresponding-adjustment status, different registry confirmation states, or different retirement eligibility, and all of that has to be tracked correctly while order volume climbs. That is the real reason carbon exchange scalability fails differently, and earlier, than scalability failures in conventional finance. The 12 Infrastructure Failure Points Behind Poor Carbon Exchange Scalability 1. Registry Mismatch Under Load At low volume, a manual reconciliation between your internal ledger and the registry’s record is manageable. At higher volume, registry confirmations arrive out of order, some fail silently, and your internal state drifts from the registry’s actual state. This single gap is the most common root cause of carbon exchange scalability complaints we see in audits. 2. Synchronous Assumptions About Asynchronous Registries Many platforms are built assuming a registry call returns instantly. In production, registries (Verra, Gold Standard, Puro, national registries) respond on their own schedule, sometimes with delays measured in hours. A platform that treats registry confirmation as synchronous will queue, time out, or double-process under real load. 3. Settlement Recalculating Instead of Reusing Execution Data If your settlement service independently recalculates price or eligibility instead of using exactly what the matching engine already decided, you get discrepancies the moment concurrent trades increase. Settlement should fulfil a commitment, not re-derive one. 4. Fee Engine Drift Across Currencies and Tiers Fee logic that works cleanly for one currency and one tier starts drifting the moment you add multi-currency settlement or tiered institutional pricing. Rounding errors that were invisible at ten trades a day become audit findings at ten thousand. 5. Stale Eligibility States Eligibility (jurisdiction, vintage, corresponding adjustment, methodology) is often checked once, at order entry, and never re-verified at execution. Under higher concurrency, the gap between “checked” and “executed” widens, and credits that were eligible when queued may not be eligible when they finally trade. 6. Concurrency Bugs in the Matching Engine A matching engine that works correctly for sequential orders can behave incorrectly under concurrent load, double-matching the same inventory, or allowing two buyers to reserve the same lot simultaneously. This is a classic carbon exchange scalability failure because it only appears once real trading volume creates genuine concurrency. 7. No Idempotency on Registry Webhooks Registries retry webhooks. If your settlement processor treats every webhook delivery as a new event instead of checking for a unique evidence identifier, a single confirmation can get applied twice, and your credit balances quietly become wrong. 8. Partial Fill Handling That Loses Track of Residuals An order for 10,000 tonnes that only fills 6,200 tonnes needs the platform to track the executed amount and the residual amount as two distinct, immutable records. Platforms that treat the original order size as the settled amount create reconciliation problems that compound with every partial fill. 9. Multi-Tenant Isolation Gaps For platforms serving multiple aggregators, project developers, or white-label clients, tenant isolation that works at low volume can leak under load: one tenant’s query load or data can bleed into another’s, a serious compliance issue as much as a technical one. 10. Database Contention on Shared Inventory Tables A single, unpartitioned inventory table becomes a bottleneck the moment several matching processes need to read and lock the same rows. This is one of the more fixable causes of poor carbon exchange scalability, but it requires re-architecting data access patterns, not just adding servers. 11. Audit Trail Gaps Under High Throughput Compliance-grade reporting needs an immutable, queryable record of every state transition – order, execution, settlement, registry transfer. Systems built for low volume often log selectively; at scale, gaps in that trail become a regulatory exposure, not just an inconvenience. 12. No Circuit Breakers for External Dependencies When a registry API slows down or a payment rail has an outage, a platform without circuit breakers will let failures cascade into the matching engine and order intake. A resilient exchange isolates external failures instead of letting them take down live trading. Why These Failures Are Specific to Carbon Markets Failure Point Why It’s Worse in Carbon Markets Than General Trading Registry mismatch External registries are not owned by the exchange and respond asynchronously Stale eligibility Eligibility depends on vintage, methodology, geography — not just price and quantity Partial fills Inventory is not fungible; eligible lots differ by attribute, not just price Multi-tenant isolation Aggregator and white-label models are far more common than in traditional exchanges Audit trail gaps Compliance regimes (Article 6, CCTS, CORSIA) require traceability generic exchanges don’t
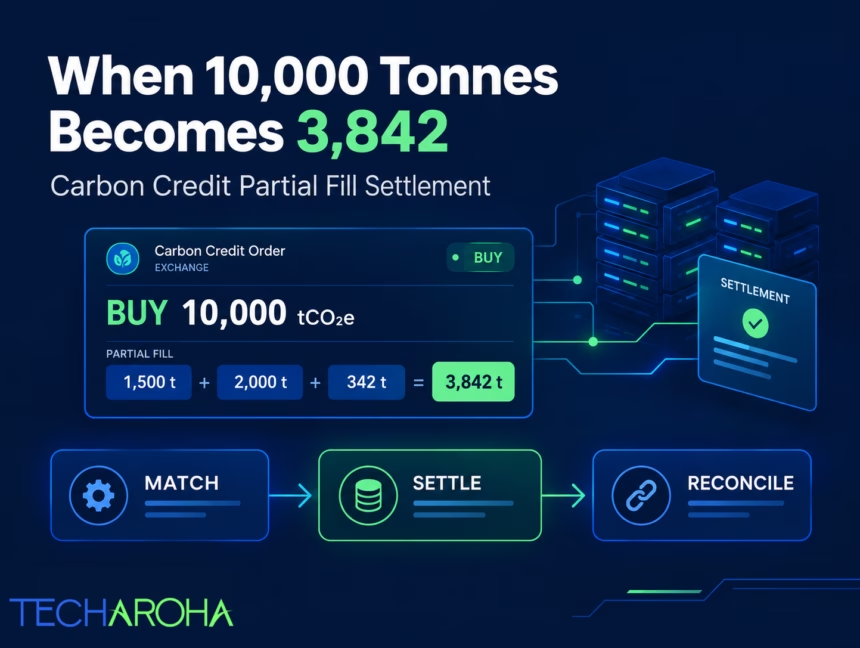
A carbon exchange can display a beautiful order book and still have fundamentally broken trading infrastructure. The real test begins when a buyer submits an order for 10,000 tonnes, but the matching engine can only execute 3,842 tonnes across multiple eligible sellers. What happens to the remaining 6,158 tonnes? More importantly: This is where carbon credit partial fill settlement becomes an architecture problem rather than a UI feature. Traditional exchange infrastructure already understands partial fills. Carbon markets make the problem harder because the underlying asset isn’t simply “10,000 units.” A carbon order can depend on vintage, methodology, geography, project, registry, authorization status, corresponding adjustment, removal/reduction classification, co-benefits, eligibility rules and available inventory.That means the matching engine cannot simply ask: “Does price match?” It needs to ask: “Does price match and does this exact inventory satisfy the buyer’s eligibility constraints at execution time?” And settlement has to preserve that decision. Why Partial Fills Are More Complicated in Carbon Markets Consider this order: Order Parameter Buyer Requirement Quantity 10,000 tCO₂e Maximum price $18/t Registry Approved registry Vintage 2022–2025 Methodology Removal Geography Eligible jurisdictions Eligibility Corporate procurement criteria Time-in-force IOC The order enters the exchange. The engine finds: But Seller D’s inventory subsequently fails an eligibility check. The executable quantity is therefore 3,840 tonnes, not 8,340. That single change creates several state transitions. Order state NEW → PARTIALLY_FILLED → CANCELLED/EXPIRED Inventory state AVAILABLE → RESERVED → TRADED → SETTLED Settlement state PENDING → PARTIALLY_SETTLED → SETTLED Registry state TRANSFER_REQUESTED → CONFIRMED / FAILED A production platform must maintain these states independently without allowing them to contradict one another. That is the core challenge behind carbon credit partial fill settlement. 1. Start With the Matching Engine, Not Settlement Settlement problems are frequently symptoms of weak execution architecture. A robust carbon exchange should separate at least these logical layers: The important architectural principle is that matching creates an execution commitment; settlement fulfils that commitment.Settlement should not independently decide what was traded. If the settlement service recalculates eligibility or price independently from the matching engine, the platform can create discrepancies between: That is precisely what an exchange operator wants to avoid. Read: The Authorization Wall: How Custom Carbon Exchanges Must Architect for Article 6 Corresponding Adjustments 2. Eligibility Must Be Part of Matching A common architecture mistake is to treat eligibility as a front-end filter. For example: “Show the buyer only CORSIA-eligible credits.” That is not enough. The eligibility decision needs to survive all the way into execution. Suppose a buyer wants 5,000 tonnes of eligible inventory. The matching engine finds three lots: Seller Available Price Eligibility Executable A 1,200 $14.80 Yes 1,200 B 2,000 $15.10 Yes 2,000 C 3,000 $15.40 No 0 The engine should not match 5,000 tonnes and “sort out eligibility later.” The correct result is: 3,200 tonnes executable + 1,800 tonnes residual. This distinction becomes especially important when eligibility can change because of: For institutional trading, eligibility should therefore be represented as a versioned execution condition, not simply a UI attribute. 3. Order Types Determine Partial-Fill Behaviour Not every order should behave the same way. A carbon exchange may support several order instructions depending on its market design. Order Type Partial Fill? Typical Behaviour Limit Yes Execute available eligible quantity and leave residual Market Usually yes Execute against eligible liquidity subject to protection rules IOC Yes Fill available quantity immediately; cancel residual FOK No Execute only if entire eligible quantity can be filled GTC Yes Leave residual active until filled/cancelled/expired GTD Yes Remain active until specified expiry Smart Order Yes Route across eligible liquidity sources For carbon credit partial fill settlement, this distinction matters because the residual order is not necessarily another settlement. The platform must clearly separate: Executed quantity from Remaining quantity For example: The settlement engine must never accidentally treat the original 10,000 tonnes as the settled amount. 4. Partial Fill Is an Execution Event, Not an Order Event This is a subtle but critical architecture decision. One order can generate multiple executions. For example: The order has therefore executed: 3,842 tonnes But the exchange has three separate execution records. Each execution should have its own immutable identifiers and economic details. At minimum: This event-level structure is what makes downstream reconciliation possible. 5. The Smart Order Router Has a Different Job A smart order router should not simply find the cheapest credit. It should find the best executable eligible liquidity according to the exchange’s routing policy. Imagine: The router can evaluate: This becomes particularly valuable when the exchange operates as an aggregation layer rather than a single order book. The router should also preserve execution provenance. If 10,000 tonnes are sourced through four venues, the platform needs to know exactly where every tonne originated. 6. The Hard Part: Carbon Credit Partial Fill Settlement This is where many marketplace architectures become fragile. Suppose: Buyer order = 10,000 tonnes The engine executes: Total: 3,842 tonnes Settlement should operate on the 3,842-tonne execution set, not the original order. A simplified flow looks like: The settlement orchestrator should maintain a state machine rather than a single Boolean such as: settled = true A more useful model is: That distinction becomes essential when registry APIs are asynchronous or unreliable. 7. Registry Confirmation Should Not Be Treated as a Synchronous Assumption Carbon exchanges often depend on external registry infrastructure. The exchange might successfully execute a trade, but the registry transfer could: Therefore: Trade execution ≠ registry settlement. The platform needs a durable settlement workflow. For example: The exact ordering can vary depending on custody and counterparty-risk design, but the state transitions must be explicit. 8. Idempotency Is Mandatory Imagine the registry confirms a transfer. Your webhook receives the confirmation. The service processes it. Then the same webhook arrives again. If the system simply says: “Transfer confirmed → add 1,500 tonnes” you have a serious accounting problem. Instead, settlement events need unique evidence identifiers. For example: The settlement processor should verify whether that evidence has already been consumed. Conceptually: This is one of the most important

Building a carbon exchange is not primarily a software decision. It is an ownership, liquidity, compliance, and time-to-market decision. Here is how founders and CTOs should actually choose between building, buying, or going white-label. You have the business model.You know who will supply the credits.You may already have project developers, corporate buyers, brokers, or investors interested.Then someone asks the uncomfortable question: “Are we building the exchange ourselves, buying existing software, or launching on a white-label platform?” That decision can determine how much control you have three years from now. Get it wrong, and you can end up with a platform that launches quickly but cannot support your compliance model, a custom system that consumes a year of capital before generating liquidity, or a white-label solution that looks like your exchange but behaves like someone else’s product. That is why the build vs buy carbon exchange decision should not be reduced to development cost. The real question is:Which implementation route gives your business the right combination of speed, control, compliance, economics and future ownership?There are three realistic routes: The right answer depends on what you are actually trying to own. Build vs Buy Carbon Exchange: Start With the Business Model, Not the Software A common mistake is starting with a feature checklist. “Does it have an order book?”“Does it support wallets?”“Does it have an admin dashboard?”“Can buyers purchase credits?” Those questions matter, but they come too late. A carbon exchange is not simply a website where tonnes are listed.Behind every transaction may be: The implementation route should therefore follow the business model and market structure. If your exchange is fundamentally different from existing platforms, customization becomes strategically important.If your model is conventional and speed is everything, buying may make sense.If you need your own brand and customer relationship without funding an entire exchange architecture from scratch, white-label can be the middle ground. The Three Carbon Exchange Routes Factor Custom Build Buy Existing Platform White-Label Initial speed Slowest Fast Fastest Upfront investment Highest Low–Medium Medium Customization Very High Limited Medium–High Brand ownership Full Depends on vendor Usually high IP ownership Negotiable/full Vendor-owned Usually vendor-owned core Registry integration Custom Depends on vendor Configurable Compliance logic Designed around your model Vendor constraints Depends on architecture Scalability Designed for your roadmap Product-dependent Depends on shared architecture Vendor dependency Lower High High Best for Strategic exchange operators Standard requirements Fast market entry But there is a more important distinction. You are not choosing between three software packages. You are choosing where your competitive advantage will live. Option 1: Build a Custom Carbon Exchange A custom build means the exchange is engineered around your requirements rather than forcing your requirements into somebody else’s product.This does not necessarily mean writing every component from zero.A competent development partner can use established engineering patterns, cloud infrastructure, security frameworks, payment infrastructure, and reusable components while custom-building the business-critical layers. Build makes sense when you need: The biggest advantage is control. You decide how credits are represented.You decide which attributes affect eligibility.You decide how orders are matched.You decide how settlement works.You decide which integrations become core infrastructure. That control becomes particularly valuable when the market evolves. A regulation changes.A registry changes its integration model.A new credit category becomes commercially important. Your buyer requires a new settlement mechanism. With a custom platform, those changes become engineering decisions rather than vendor negotiations. But a custom build has a serious disadvantage. Time. A serious exchange cannot be treated like a standard marketplace website. Architecture, security, testing, registry integrations, matching, settlement, and operational controls all take engineering effort. That means custom development is usually a poor choice for a company that simply wants to “test whether people will buy carbon credits.” It becomes much more attractive when the exchange itself is intended to become a long-term business asset. Option 2: Buy an Existing Carbon Exchange Platform Buying software is attractive because it appears to eliminate the hardest part of the problem. The vendor has already built: You configure it and launch. For a company with standard requirements, this can be perfectly reasonable. Buy when: But there is a question founders often forget to ask: What happens when your business becomes more successful than the software you bought? That is the real risk. A platform can be excellent today and still become restrictive tomorrow. Imagine that your exchange eventually needs: If the vendor cannot support those changes, your growth becomes constrained by someone else’s product roadmap. The hidden cost of buying The licence fee is only one part of the equation. You should evaluate: Licence + integration + customization + migration + vendor dependency + switching cost A cheap platform can become expensive if every meaningful change requires paid customization. Option 3: White-Label Carbon Exchange This is where the decision becomes more interesting. A white-label carbon exchange allows you to launch under your own brand while using an underlying platform infrastructure provided by another company. For a company that wants market presence quickly, this can be attractive.You can potentially get: without financing every component of the platform from scratch.The critical word, however, is architecture. Not every white-label solution is actually suitable for carbon markets. A generic crypto exchange with a new logo is not automatically a carbon exchange. Carbon credits have attributes that influence whether a transaction is valid. For example: A serious white-label architecture therefore needs more than a branded front end.It needs appropriate tenant isolation, configurable business rules, registry integrations, permissions, transaction controls, and compliance-aware workflows. Read our Article- What Does a Carbon Exchange Actually Cost to Build? A Module-by-Module Breakdown The Build vs Buy Carbon Exchange Decision Matrix Instead of asking which route is “best,” score each route against your actual requirements. Decision Factor Build Buy White-Label Budget sensitivity ★★ ★★★★★ ★★★★ Speed to launch ★★ ★★★★ ★★★★★ Product differentiation ★★★★★ ★★ ★★★ Platform control ★★★★★ ★★ ★★★ Compliance customization ★★★★★ ★★ ★★★★ Registry flexibility ★★★★★ ★★–★★★ ★★★ Long-term ownership ★★★★★ ★★ ★★★ Engineering independence ★★★★★ ★★ ★★★ MVP validation ★★★ ★★★★★ ★★★★★

A compliance buyer at an international airline opens your platform, filters for Article 6.4-eligible inventory, and clears an order against a lot of what your database calls “available credits.” Forty minutes later, the host country’s national authority issues a Letter of Authorization on a completely unrelated administrative timeline, and the units the airline just bought quietly stop being what they were sold as. The row in your ledger didn’t change. The legal reality underneath it did. This is not a hypothetical edge case dreamed up for a conference panel. It is the structural consequence of how the Paris Agreement Crediting Mechanism (PACM) actually works, and it is the single most under-engineered problem in carbon market software right now. Any platform still treating credits as flat, static rows is building on a foundation that the regulation itself has already made obsolete. What every serious exchange, registry, and compliance desk needs instead is a carbon credit state machine architecture, and almost nobody has one. Why a Single Credit Now Has Two Legal Identities Under Article 6.4, a project doesn’t just issue “carbon credits.” It issues Article 6.4 Emission Reductions, or A6.4ERs, and those units arrive in one of two legal states. If the host country has not authorized a unit for international use, it is issued and held as a Mitigation Contribution Unit (MCU) usable domestically, for results-based climate finance, or for a country’s own NDC, but legally barred from crossing a border for compliance purposes. If the host country has authorized the unit and applied a corresponding adjustment, it becomes an Authorized Emission Reduction (AER), eligible to move internationally and clear against schemes like CORSIA. Here is the part that breaks flat databases: a unit issued as an MCU is not permanently an MCU. Host countries can grant retroactive authorization, and the moment they do, that unit’s legal identity flips – it stops being a domestically-contained MCU and becomes an internationally transferable AER, provided it hasn’t already been transferred out of the mechanism registry. The reverse containment rule matters just as much: MCUs remain confined to transactions within the mechanism registry until that authorization event happens. A platform’s asset ledger is not looking at one static object. It’s looking at a unit with a lifecycle, governed by a decision made by a national authority on a timeline your engineering team does not control and often can’t even observe in real time. This is exactly why a carbon credit state machine architecture has to be the starting assumption for any exchange handling Article 6.4 inventory, not a feature bolted on after the first compliance incident. The Structural Problem: What Happens When Your Ledger Treats Credits as Fungible Rows Picture the default approach most platforms take, because it’s the same approach that has worked fine for years of pre-Article-6 voluntary credits: a table with a credit ID, a project reference, a vintage, a quantity, and a status column that says “available,” “retired,” or “sold.” Fungible. Flat. Fast to query. Now put an MCU into that table. The status column says “available.” A compliance buyer, say, an airline covering CORSIA obligations – filters inventory, sees the lot, and clears the trade. Nothing in the schema stopped this, because nothing in the schema knew the difference between an MCU and an AER in the first place. The airline has now taken legal ownership of a unit that cannot clear their compliance ledger, because it was never authorized for international transfer at the moment of sale. Nobody committed fraud. The seller may not have even realized the lot hadn’t cleared host-country authorization. The matching engine did exactly what matching engines do: it matched a buy order against available inventory. The failure isn’t behavioral. It’s architectural. A platform without a carbon credit state machine architecture cannot distinguish between an MCU and an AER at the only moment that legally matters: the instant before settlement, because it was never built to track legal state as a first-class property of the asset. This is the exact failure mode regulators are now scrutinizing under anti-greenwashing enforcement regimes. It’s not enough to detect the mismatch after the fact through a reconciliation job. The question examiners are asking exchange operators is whether the platform’s data model made an unauthorized clearing possible in the first place. If the answer is yes, that’s not a footnote. That’s an exposure line item with a compliance buyer’s name attached to it. The Software Architecture Solution: A Conditional State-Machine Pattern for the Asset Ledger The fix is not a better compliance checkbox, and it’s not a nightly reconciliation batch that tells you about a mismatch twelve hours after it already cleared. The fix is redesigning the asset ledger so that a unit’s authorization status is a governed state, not a display label. This is the core of a functioning carbon credit state machine architecture. Here’s the shape of it, stripped to its engineering bones. Why “Just Add a Status Filter” Doesn’t Solve This The tempting shortcut here is the same one platforms reached for with dual-claiming risk: add a filter on the front end so buyers “should” only see eligible inventory, and add an attestation checkbox at checkout confirming the buyer understands the unit’s authorization status. This does almost nothing, for the same reason it never works elsewhere. A front-end filter is a display convenience, not an architectural guarantee; it doesn’t stop an API call, an internal admin override, or a race condition where a unit’s status changes between page load and order submission from clearing an ineligible trade anyway. An attestation checkbox shifts liability onto a buyer’s understanding of a UN mechanism most corporate procurement teams have never had to parse line by line. Neither approach constitutes a carbon credit state machine architecture. Both are policy dressed up as engineering, and regulators evaluating anti-greenwashing controls are no longer satisfied by the distinction between “we tell the buyer” and “we structurally prevent the mismatch.” They’re asking whether the platform’s asset ledger could have allowed this trade