
Indian carbon credit aggregators are sitting on an asset they don’t fully control: their own inventory. Ask most aggregators how a deal actually closes today, and the answer is some combination of WhatsApp threads, Excel trackers, broker introductions, and a third-party marketplace listing that takes a cut of every tonne sold. The projects are real. The credits are real. The buyers exist. What’s missing is a system the aggregator actually owns. That’s the gap a private carbon marketplace in India is built to close – a branded, purpose-built trading environment where the aggregator, not an intermediary, controls listing, matching, pricing, and settlement. This isn’t a theoretical exercise. It’s an infrastructure decision that directly affects margin, buyer trust, and how fast an aggregator can scale beyond the projects they can personally track in a spreadsheet. What Is a Private Carbon Marketplace? A private carbon marketplace India is a dedicated trading platform, built and branded around a single aggregator or intermediary, where sellers (project developers) and buyers (corporates, brokers, ESG platforms) transact directly under rules the aggregator defines. It’s “private” in the sense that it isn’t a shared, multi-vendor bazaar. The aggregator decides: Unlike a generic listing page, a real private carbon marketplace India is an operating system for the aggregator’s trading business – inventory, buyers, sellers, verification, and settlement all living in one place instead of scattered across tools that were never designed to talk to each other. Why Indian Carbon Aggregators Are Considering Their Own Platforms Three forces are pushing this conversation forward for aggregators across India right now. None of this means every aggregator needs a platform tomorrow. It means the decision is now worth evaluating seriously, with real numbers, rather than deferring indefinitely. Read- Carbon Exchange Scalability: 12 Failure Points to Fix Now Third-Party Marketplace vs Your Own Marketplace Factor Third-Party Marketplace Private Carbon Marketplace India Brand ownership Buyer relationship belongs to the marketplace Buyer relationship belongs to the aggregator Commission Per-transaction fee, typically ongoing One-time build + ownership of margin Data control Limited visibility into buyer behaviour Full inventory, buyer and transaction data Customization Fixed workflow, rules, categories Rules, pricing and workflow built around your model Registry integration Often generic or manual Can be built around your specific registries Buyer trust signals Shared with every other seller on the platform Dedicated to your track record and projects Scalability Bound by the marketplace’s roadmap Bound only by your own roadmap The trade-off is straightforward: a third-party marketplace is faster to start on, but every trade routed through it strengthens someone else’s platform, not yours. A private carbon marketplace India is a longer-term commitment that converts recurring fees into a durable business asset. What an Aggregator’s Private Marketplace Actually Needs This is where most conversations about a private carbon marketplace India go wrong. People imagine a storefront with a “buy now” button. A functioning marketplace needs considerably more underneath it: A marketplace that skips any of these isn’t a smaller version of a private carbon marketplace India — it’s a different, weaker product that will need to be rebuilt the moment volume grows. Architecture of a Private Carbon Marketplace At a high level, the architecture behind a private carbon marketplace India looks like this: Users → Marketplace UI → API Gateway → Authentication/RBAC → Marketplace Engine → Credit Inventory & Project Management → Eligibility/Compliance Engine → Matching & Order Management → Pricing/Fee Engine → Transaction & Settlement Layer → Registry/API Integrations → Retirement/Transfer Tracking → Reporting & Audit Logs Each user type – admin, aggregator, buyer, seller/project developer, and registry/external systems interacts with its own layer of this architecture, with permissions and workflows built around what that role should and shouldn’t be able to see or do. A note on blockchain: it’s often assumed to be mandatory for anything carbon-related. It isn’t. Blockchain is a genuinely useful layer when tokenization, provenance tracking, or immutable transaction records are actual business requirements — for example, when buyers demand a verifiable, tamper-proof trail for a credit’s history. For many aggregators, a well-architected database with strong audit logging accomplishes the same trust objective without the added complexity. The right call depends on the aggregator’s buyers and compliance obligations, not on what sounds impressive in a pitch. Registry & External-System Integrations A private carbon marketplace India doesn’t operate in isolation. It needs to talk to the systems that determine whether a credit is actually valid, available, and transferable – carbon registries, verification bodies, and in some cases payment or banking rails for settlement. This is one of the more underestimated parts of the build. Registries don’t always respond instantly, formats vary, and a credit that looks available in your internal system can be pending or already retired at the registry level. A marketplace built without this in mind will eventually show buyers inventory that isn’t actually tradeable — a fast way to lose trust with exactly the institutional buyers an aggregator is trying to attract. Where AI Helps and Where Engineering Still Matters AI has a real, useful role inside a private carbon marketplace: surfacing anomalies in project documentation, flagging inconsistent data across submissions, assisting with buyer-seller matching suggestions, and summarizing project information for faster review. What AI does not replace is the underlying engineering: the eligibility rules, the registry integration logic, the settlement state machine, the audit trail. Those need to be deterministic, auditable, and correct every time — not probabilistic. Treating AI as a layer on top of solid infrastructure, rather than a substitute for it, is the difference between a marketplace that scales and one that produces confusing edge cases the moment volume increases. Security, Auditability and Data Integrity Aggregators building this kind of platform are handling buyer KYC data, transaction records, project documentation and — increasingly — data that compliance teams may eventually want to audit. That makes a few things non-negotiable: These aren’t features to add later. They’re structural decisions that are far cheaper to build in from day one than to retrofit after the platform is already
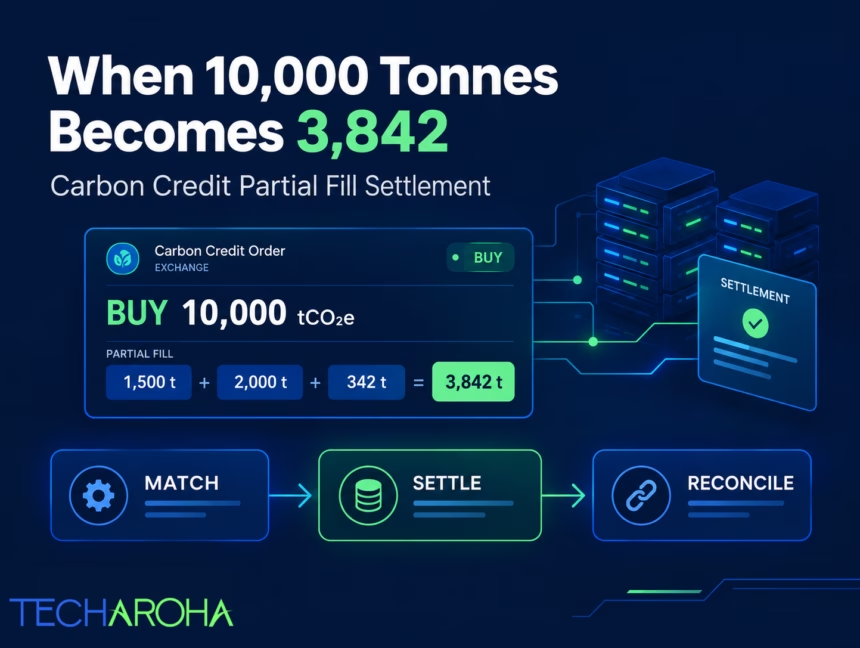
A carbon exchange can display a beautiful order book and still have fundamentally broken trading infrastructure. The real test begins when a buyer submits an order for 10,000 tonnes, but the matching engine can only execute 3,842 tonnes across multiple eligible sellers. What happens to the remaining 6,158 tonnes? More importantly: This is where carbon credit partial fill settlement becomes an architecture problem rather than a UI feature. Traditional exchange infrastructure already understands partial fills. Carbon markets make the problem harder because the underlying asset isn’t simply “10,000 units.” A carbon order can depend on vintage, methodology, geography, project, registry, authorization status, corresponding adjustment, removal/reduction classification, co-benefits, eligibility rules and available inventory.That means the matching engine cannot simply ask: “Does price match?” It needs to ask: “Does price match and does this exact inventory satisfy the buyer’s eligibility constraints at execution time?” And settlement has to preserve that decision. Why Partial Fills Are More Complicated in Carbon Markets Consider this order: Order Parameter Buyer Requirement Quantity 10,000 tCO₂e Maximum price $18/t Registry Approved registry Vintage 2022–2025 Methodology Removal Geography Eligible jurisdictions Eligibility Corporate procurement criteria Time-in-force IOC The order enters the exchange. The engine finds: But Seller D’s inventory subsequently fails an eligibility check. The executable quantity is therefore 3,840 tonnes, not 8,340. That single change creates several state transitions. Order state NEW → PARTIALLY_FILLED → CANCELLED/EXPIRED Inventory state AVAILABLE → RESERVED → TRADED → SETTLED Settlement state PENDING → PARTIALLY_SETTLED → SETTLED Registry state TRANSFER_REQUESTED → CONFIRMED / FAILED A production platform must maintain these states independently without allowing them to contradict one another. That is the core challenge behind carbon credit partial fill settlement. 1. Start With the Matching Engine, Not Settlement Settlement problems are frequently symptoms of weak execution architecture. A robust carbon exchange should separate at least these logical layers: The important architectural principle is that matching creates an execution commitment; settlement fulfils that commitment.Settlement should not independently decide what was traded. If the settlement service recalculates eligibility or price independently from the matching engine, the platform can create discrepancies between: That is precisely what an exchange operator wants to avoid. Read: The Authorization Wall: How Custom Carbon Exchanges Must Architect for Article 6 Corresponding Adjustments 2. Eligibility Must Be Part of Matching A common architecture mistake is to treat eligibility as a front-end filter. For example: “Show the buyer only CORSIA-eligible credits.” That is not enough. The eligibility decision needs to survive all the way into execution. Suppose a buyer wants 5,000 tonnes of eligible inventory. The matching engine finds three lots: Seller Available Price Eligibility Executable A 1,200 $14.80 Yes 1,200 B 2,000 $15.10 Yes 2,000 C 3,000 $15.40 No 0 The engine should not match 5,000 tonnes and “sort out eligibility later.” The correct result is: 3,200 tonnes executable + 1,800 tonnes residual. This distinction becomes especially important when eligibility can change because of: For institutional trading, eligibility should therefore be represented as a versioned execution condition, not simply a UI attribute. 3. Order Types Determine Partial-Fill Behaviour Not every order should behave the same way. A carbon exchange may support several order instructions depending on its market design. Order Type Partial Fill? Typical Behaviour Limit Yes Execute available eligible quantity and leave residual Market Usually yes Execute against eligible liquidity subject to protection rules IOC Yes Fill available quantity immediately; cancel residual FOK No Execute only if entire eligible quantity can be filled GTC Yes Leave residual active until filled/cancelled/expired GTD Yes Remain active until specified expiry Smart Order Yes Route across eligible liquidity sources For carbon credit partial fill settlement, this distinction matters because the residual order is not necessarily another settlement. The platform must clearly separate: Executed quantity from Remaining quantity For example: The settlement engine must never accidentally treat the original 10,000 tonnes as the settled amount. 4. Partial Fill Is an Execution Event, Not an Order Event This is a subtle but critical architecture decision. One order can generate multiple executions. For example: The order has therefore executed: 3,842 tonnes But the exchange has three separate execution records. Each execution should have its own immutable identifiers and economic details. At minimum: This event-level structure is what makes downstream reconciliation possible. 5. The Smart Order Router Has a Different Job A smart order router should not simply find the cheapest credit. It should find the best executable eligible liquidity according to the exchange’s routing policy. Imagine: The router can evaluate: This becomes particularly valuable when the exchange operates as an aggregation layer rather than a single order book. The router should also preserve execution provenance. If 10,000 tonnes are sourced through four venues, the platform needs to know exactly where every tonne originated. 6. The Hard Part: Carbon Credit Partial Fill Settlement This is where many marketplace architectures become fragile. Suppose: Buyer order = 10,000 tonnes The engine executes: Total: 3,842 tonnes Settlement should operate on the 3,842-tonne execution set, not the original order. A simplified flow looks like: The settlement orchestrator should maintain a state machine rather than a single Boolean such as: settled = true A more useful model is: That distinction becomes essential when registry APIs are asynchronous or unreliable. 7. Registry Confirmation Should Not Be Treated as a Synchronous Assumption Carbon exchanges often depend on external registry infrastructure. The exchange might successfully execute a trade, but the registry transfer could: Therefore: Trade execution ≠ registry settlement. The platform needs a durable settlement workflow. For example: The exact ordering can vary depending on custody and counterparty-risk design, but the state transitions must be explicit. 8. Idempotency Is Mandatory Imagine the registry confirms a transfer. Your webhook receives the confirmation. The service processes it. Then the same webhook arrives again. If the system simply says: “Transfer confirmed → add 1,500 tonnes” you have a serious accounting problem. Instead, settlement events need unique evidence identifiers. For example: The settlement processor should verify whether that evidence has already been consumed. Conceptually: This is one of the most important

Ask five carbon exchange founders what it costs to build their platform, and you’ll get five different numbers, none of which they fully trust. That’s not because nobody knows. It’s because most of the numbers floating around “$50k for an MVP,” “$2 million for an institutional-grade exchange” come from vendors quoting a category, not a scope. And scope is the entire game. We’ve architected and built live carbon market infrastructure, including Carbon Plant, an FSA-registered NFT-based carbon credit exchange, and Planet First Registry, the registry layer underneath it. So this isn’t a theoretical pricing exercise; it’s the same breakdown we walk actual founders through before they commit budget. This article exists for one reason: to give you a real, defensible carbon exchange development cost framework, module by module, complexity tier by complexity tier, before you sign with anyone. If You’re Reading This, You’re Probably Asking One of These Questions If any of those sound familiar, keep reading. If you’re purely comparison-shopping template exchanges with no compliance requirements, this probably isn’t the right guide for you. Why Carbon Exchange Development Cost Estimates Vary So Wildly? Most published numbers ignore the variable that actually moves the budget: which modules you’re building, and how deep each one needs to go. A carbon exchange isn’t one product. It’s a stack of independent systems that happen to share a brand: A vendor quoting “$60k” is very likely quoting a shell: a UI, a basic order form, and a single database, with no real matching logic, no registry sync, and no compliance layer. A vendor quoting “$600k” may be pricing a multi-jurisdiction, multi-registry institutional platform with dedicated matching workers per tenant. Neither number is wrong. They’re just answering different questions. Carbon Exchange Development Cost by Module Here’s the breakdown we actually use in scoping conversations, organized by the components that make up a functioning exchange. Module What It Covers Relative Cost Weight Matching Engine Order book, trade execution, partial fills, fractional quantities High Registry Integration Verra, Gold Standard, Puro, ACCU, or custom registry sync High Credit Tokenization NFT or ledger-based representation of credits, lifecycle states Medium–High KYC/KYB & Compliance Identity verification, jurisdiction-aware onboarding rules Medium Fee Engine & Settlement Tiered fees, multi-currency settlement, reconciliation Medium Wallet & Custody Credit and fiat/stablecoin custody, transfer, security Medium Multi-Tenant/White-Label Layer Tenant isolation, per-tenant branding and config High (if included) Reporting & Audit Trails Compliance-ready trade history, exportable reports Low–Medium A single-registry, single-currency exchange with basic KYC sits at the lower end of a build. Add multi-registry connectivity, multi-tenancy, and jurisdiction-specific compliance rulesets (CCTS, Article 6, CORSIA-domestic, EU ETS), and the same “exchange” becomes a materially larger engineering project. Read- White-Label Carbon Trading Platform: Launch in Weeks Now. The Three Factors That Actually Drive Carbon Exchange Development Cost 1. Complexity Tier Every build falls into one of three tiers: Every tier up adds engineering months, not just feature checkboxes. This is the single biggest driver of carbon exchange development cost, and the one most quotes gloss over. 2. Jurisdiction and Regulatory Scope A platform serving one compliance regime is a fundamentally different build than one serving five. Article 6.4 eligibility logic, CCTS-specific reporting, CBAM-adjacent import calculations, and CORSIA-domestic rules don’t share a codebase cleanly. Each jurisdiction you support adds configuration, testing, and often legal review to the timeline. 3. Integration Depth How many registries does the platform need to talk to? Does it need to reconcile against Verra and Gold Standard and a national registry simultaneously? Does settlement need to support fiat, stablecoin, and direct bank transfer? Every integration is a dependency you don’t control, and dependencies you don’t control take longer to harden than the code you write yourself. Build vs. White-Label: What Actually Changes the Number A properly engineered white-label carbon exchange built on genuine multi-tenant architecture with tenant-isolated data and per-tenant registry routing compresses timeline and cost dramatically compared to a from-scratch build, because the matching engine, fee logic, and compliance framework already exist. You’re paying primarily for tenant onboarding, branding, and jurisdiction-specific configuration, not for rebuilding the core exchange. A from-scratch build makes sense when your compliance requirements, tenant model, or credit types don’t fit any existing architecture, or when owning the entire codebase is a strategic requirement for your investors or regulators. Neither path is inherently cheaper in all cases. It depends entirely on how far your requirements sit from a standard exchange pattern. What Most Founders Get Wrong When Budgeting A Simple Framework for Getting an Accurate Number Before you ask any vendor for a quote, have answers ready for: Any vendor who can give you a real carbon exchange development cost estimate without asking these questions first is quoting a template, not your platform. Where This Leaves You The honest answer to “how much does it cost to build a carbon exchange” is: it depends on which of the eight modules above you actually need, at what depth, across how many jurisdictions. That’s not a dodge; it’s the actual shape of the decision. What we can do is take your specific scope the registries, the jurisdictions, the tenant model, the compliance depth and turn it into a preliminary cost estimate you can actually take to a board, an investor, or your own internal budget review. Get a Preliminary Cost Estimate for your carbon exchange build, scoped against your actual registries, jurisdictions, and compliance requirements not a generic template. Want to sanity-check the number yourself first? We’re building a Carbon Platform Cost Calculator that maps your requirements to a realistic range before you ever get on a call. (Related reading: our guide to building a Carbon Credit Exchange Platform, our white-label carbon trading platform breakdown, and our carbon registry interoperability piece.)

Every regional forestry aggregator we’ve spoken to this year has the same quiet frustration sitting under their pitch deck. They’re sitting on a few hundred verified projects – methane capture, avoided deforestation, agroforestry blocks spread across three or four states and every single credit gets sold through somebody else’s marketplace. Somebody else’s brand. Somebody else’s 5–10% commission, taken off the top of every trade, forever. Ask an aggregator managing 300+ projects what that commission actually costs them over a five-year horizon, and most haven’t run the number. Once they do, the room goes quiet. On $40M of annual trade volume, an 8% marketplace cut is $3.2M a year handed to a third party for what amounts to hosting an order book. That’s not a fee. That’s a tax on not owning your own infrastructure. So the aggregator goes looking for an alternative: build our own exchange. And that’s where the second wall shows up. A serious matching and clearing engine – the kind that can survive a compliance audit, handle fractional credit settlement, and route trades without corrupting a ledger takes a competent engineering team 12 to 18 months to build from a blank repository. Most aggregators don’t have 18 months of runway to spend on infrastructure before they’ve sold a single credit through it. This piece is for the people caught in that exact gap: aggregator CEOs tired of paying rent on someone else’s venue, regional brokerages that want a compliant trading brand of their own, and platform operators trying to figure out whether they should be the one licensing multi-tenant infrastructure to all of the above. We’re not selling you a shrink-wrapped product here. We’re walking through how a serious engineering team actually architects a white-label carbon trading platform built for multi-tenancy, so you have a real technical benchmark before your next build, license, or outsourcing conversation. The Real Industry Friction: Two Bad Options, No Third Path Talk to enough project developers and a pattern emerges. They’re stuck choosing between two options that both cost them something they can’t get back. Neither of these is really a choice. It’s a trade-off between bleeding money slowly and bleeding time you don’t have. The market has quietly created a third option that almost nobody outside specialist engineering circles talks about clearly: a white-label carbon trading platform built on multi-tenant SaaS architecture, where one underlying exchange engine powers dozens of independently branded, independently governed sub-exchanges. The difference between this and generic “white-label” pitches you’ve probably already seen from crypto-exchange vendors is architectural, not cosmetic. A crypto white-label slaps a new logo on a shared front end. A properly engineered white-label carbon trading platform for carbon aggregators has to isolate tenant data at the database layer, run independent matching logic per tenant, and route registry connections separately for every sub-exchange because carbon compliance obligations don’t forgive shortcuts the way a token swap does. What Changed Between January and August 2026 and Why It Matters Here Carbon market infrastructure has moved fast this year, and almost every shift makes the case for multi-tenant architecture stronger, not weaker. Put together, these shifts describe a market where owning your venue’s brand and your venue’s compliance logic are becoming the same requirement, not two separate nice-to-haves. Architecting a Multi-Tenant Carbon Exchange: The Four Layers That Actually Matter Strip away the marketing language, and a genuinely multi-tenant white-label carbon trading platform rests on four architectural decisions. Get any one of them wrong and the “weeks, not months” promise quietly becomes another 12-month build. 1. Tenant-Isolated Database Schemas with Row-Level Security The foundational decision is how tenant data actually sits in the database, because this single choice determines both your security posture and your ability to onboard new aggregators quickly. RLS done properly means a compliance auditor reviewing Tenant A’s trade history can never accidentally see so much as a row header belonging to Tenant B, even under a misconfigured application query. That’s not a nice-to-have. That’s the difference between a platform an institutional buyer will sign with and one their legal team kills in diligence. 2. Dedicated Matching Worker Threads Per Tenant This is the layer most white-label vendors get wrong, because it’s tempting to run one shared matching engine across every tenant to save infrastructure cost. Don’t. Read: Carbon Trading Platform Revenue Model: Complete Breakdown 3. Dynamic API Routing and Registry Connectivity Per Tenant A multi-tenant carbon exchange isn’t just serving different logos to different users; it’s routing genuinely different backend connections depending on which tenant a request belongs to. Routing Concern Single-Tenant Approach Multi-Tenant SaaS Approach Registry connections One hardcoded integration (e.g., Verra only) Dynamic per-tenant registry mapping (Verra, Gold Standard, Puro, ACCU) Fee schedules One fee logic for the whole exchange Per-tenant fee configuration, enforced at the API gateway Branding & domain Single domain, single UI theme Tenant-specific subdomain, white-label theme, and email templates Compliance ruleset One jurisdiction’s rules baked into logic Configurable ruleset per tenant (CCTS, ACCU, CORSIA-domestic, EU ETS) Onboarding new tenant Requires a new deployment New tenant record + config, live same week The dynamic routing layer is what actually collapses the 12–18 month build into weeks because standing up a new sub-exchange stops being an engineering project and becomes a configuration task: create the tenant record, assign the registry mappings, set the fee schedule, apply the brand theme, go live. 4. Compliance-Aware Tenant Governance The fourth layer is the one institutional buyers actually probe hardest during diligence, and it’s the one generic exchange-in-a-box vendors almost never build properly: governance controls that let a platform operator enforce baseline compliance standards across every tenant, while still letting each aggregator run their own branded venue. Weeks, Not Months: What the Compressed Timeline Actually Looks Like None of this works as a slide-deck promise unless the phased rollout is genuinely realistic. Here’s what a properly architected multi-tenant core makes possible for a new tenant going live: Compare that to the 12–18 month timeline of building a matching and clearing engine from a blank